BofA美銀總經與美股EPS就業分析報告
2026-08-12 · 含原圖
這是一份針對 image.png 的詳細繁體中文分析報告:
圖片分析報告
1. 圖片類型與整體說明
- 圖片類型:機構級金融投資研究報告頁面截圖(出處為 BofA Global Research / 美國銀行全球研究部)。
- 主題內容:探討全球總體經濟環境、美股企業獲利(EPS)預期、美國非農就業市場動態、聯準會(Fed)貨幣政策走勢,以及各大資產類別的年初至今(YTD)表現。
- 版面佈局:
- 頂部:深藍色主題橫幅標題。
- 中部:四個以粗體字為首的重點分析段落(包含資產報酬率數據與巨觀經濟邏輯)。
- 下半部:標題為
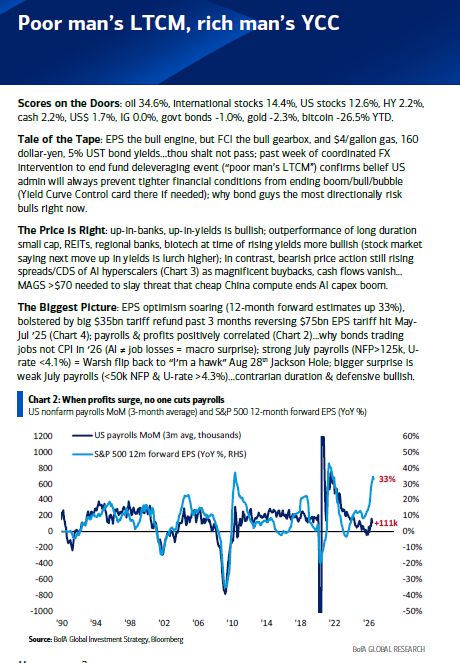
Chart 2的雙 Y 軸折線圖,呈現 1990 年至 2026 年(歷史與預估)美股 EPS 與非農就業數據的相關性。
2. 所有可見文字擷取(逐字還原)
頂部標題
Poor man’s LTCM, rich man’s YCC
內文分析段落
-
Scores on the Doors:
Scores on the Doors: oil 34.6%, International stocks 14.4%, US stocks 12.6%, HY 2.2%, cash 2.2%, US$ 1.7%, IG 0.0%, govt bonds -1.0%, gold -2.3%, bitcoin -26.5% YTD. -
Tale of the Tape:
Tale of the Tape: EPS the bull engine, but FCI the bull gearbox, and $4/gallon gas, 160 dollar-yen, 5% UST bond yields...thou shalt not pass; past week of coordinated FX Intervention to end fund deleveraging event (“poor man’s LTCM”) confirms belief US admin will always prevent tighter financial conditions from ending boom/bull/bubble (Yield Curve Control card there if needed); why bond guys the most directionally risk bulls right now. -
The Price Is Right:
The Price Is Right: up-in-banks, up-in-yields is bullish; outperformance of long duration small cap, REITs, regional banks, biotech at time of rising yields more bullish (stock market saying next move up in yields is lurch higher); in contrast, bearish price action still rising spreads/CDS of AI hyperscalers (Chart 3) as magnificent buybacks, cash flows vanish... MAGS >$70 needed to slay threat that cheap China compute ends AI capex boom. -
The Biggest Picture:
The Biggest Picture: EPS optimism soaring (12-month forward estimates up 33%), bolstered by big $35bn tariff refund past 3 months reversing $75bn EPS tariff hit May-Jul ’25 (Chart 4); payrolls & profits positively correlated (Chart 2)...why bonds trading jobs not CPI in ’26 (AI ≠ job losses = macro surprise); strong July payrolls (NFP >125k, U-rate <4.1%) = Warsh flip back to “I’m a hawk” Aug 28th Jackson Hole; bigger surprise is weak July payrolls (<50k NFP & U-rate >4.3%)...contrarian duration & defensive bullish.
圖表區塊(Chart 2)
- 圖表主標題:
Chart 2: When profits surge, no one cuts payrolls - 圖表副標題:
US nonfarm payrolls MoM (3-month average) and S&P 500 12-month forward EPS (YoY %) - 圖例說明:
- 深藍色線:
US payrolls MoM (3m avg, thousands)(左 Y 軸) - 天藍色線:
S&P 500 12m forward EPS (YoY %, RHS)(右 Y 軸) - 左 Y 軸刻度:
1200,1000,800,600,400,200,0,-200,-400,-600,-800,-1000 - 右 Y 軸刻度:
60%,50%,40%,30%,20%,10%,0%,-10%,-20%,-30%,-40%,-50% - X 軸年份刻度:
'90,'94,'98,'02,'06,'10,'14,'18,'22,'26 - 圖表關鍵數據標籤:
- 紅色字體標籤:
33% - 黑/紅字體標籤:
+111k - 頁尾標註:
Source: BofA Global Investment Strategy, BloombergBofA GLOBAL RESEARCH
3. 結構化內容還原
(一)資產類別年初至今報酬率(Scores on the Doors)
| 資產類別 (Asset Class) | 年初至今報酬率 (YTD Return) | 表現評語 |
|---|---|---|
| 原油 (Oil) | +34.6% | 表現最佳的實體商品 |
| 國際股票 (International stocks) | +14.4% | 雙位數強勁成長 |
| 美股 (US stocks) | +12.6% | 美國大盤表現優異 |
| 高收益債 (HY) | +2.2% | 小幅正報酬 |
| 現金 (Cash) | +2.2% | 提供穩健基礎收益 |
| 美元 (US$) | +1.7% | 微幅升值 |
| 投資級債 (IG) | 0.0% | 持平 |
| 政府債券 (Govt bonds) | -1.0% | 輕微虧損 |
| 黃金 (Gold) | -2.3% | 小幅回檔 |
| 比特幣 (Bitcoin) | -26.5% | 表現最差的加密資產 |
(二)四大宏觀觀察重點摘要
- 市場驅動引擎(Tale of the Tape): - 企業每股盈餘(EPS)是牛市的主引擎,金融情勢指數(FCI)則是變速箱。 - 原油 \$4/加侖、美元/日圓 160、美債殖利率 5% 為重要警戒關卡。 - 政策面干預(如外匯協調干預解除基金去槓桿危機)反映美國政府傾向阻止金融緊縮打斷牛市或泡沫(必要時將啟用 YCC 殖利率曲線控制)。
- 價格行為解讀(The Price Is Right): - 銀行股與殖利率同升屬於多頭訊號;長存續期小盤股、REITs、生技股在殖利率上升期表現優異更具多頭意義。 - AI 超大型科技公司(Hyperscalers)信用違約交換(CDS)擴大,庫藏股與現金流減少顯示潛在警訊;MAGS 需維持在 \$70 以上以抵禦中國廉價算力對 AI 資本支出熱潮的衝擊。
- 宏觀大局(The Biggest Picture): - 預估未來 12 個月 EPS 年增率飆升至 33%。 - 數據顯示就業人數與企業利潤呈現高度正相關;2026 年債券市場的交易核心在於就業數據而非 CPI。 - 若 7 月非農就業數據強勁(NFP > 125k, 失業率 < 4.1%),Warsh 可能會在 8 月 28 日 Jackson Hole 年會上重回鷹派立場;反之若就業疲軟(NFP < 50k, 失業率 > 4.3%),則有利於反向長存續期資產與防禦性板塊。
4. 視覺元素與設計細節
- 配色計畫:採用 Bank of America 的標準企業識別色(經典深藍色
#002060作為 Header 及主要圖表線條,搭配天藍色作為副線條與重點標記)。 - 數據強調:圖表中特地以紅色文字標註
33%(EPS YoY 高點預測),以及以黑色/紅色標註+111k(就業月增長數據),吸引讀者目光至最新數據節點。 - 時間軸廣度:Chart 2 的 X 軸時間跨度達 36 年(1990 至 2026 年),完整歷經 2000 網路泡沫、2008 金融危機、2020 疫情暴跌與極端反彈,用以展現歷史規律。
5. 上下文與推測用途
- 資料來源:美國銀行全球研究部(BofA Global Research / Bloomberg)。
- 目標受眾:機構法人經理人、總體經濟分析師與高淨值投資者。
- 主要用途: 1. 作為每週或定期宏觀資產配置報告(如 BofA 著名的 The Flow Show 報告系列)的核心觀點輸出。 2. 協助投資人釐清當前市場「利潤暴增時企業不會裁員」的宏觀規律,進而評估美股 EPS 與美債殖利率的未來動向。
BofA美銀總經與美股EPS就業分析報告
本圖為美國銀行(BofA Global Research)發布的宏觀投資策略研究報告截圖,主題為「Poor man’s LTCM, rich man’s YCC」。報告詳述了資產 YTD 表現、美股 EPS 與非農就業市場的高相關性(預估 12 個月 EPS 成長率達 33%),並分析了美債殖利率、AI 資本支出及央行政策對市場的影響。