高盛美股宏觀與市場結構分析
2026-09-16 · 含原圖
圖片分析報告:美股宏觀與市場結構研究筆記
1. 圖片類型與整體說明
- 圖片類型:投資銀行 / 機構研究部門的市場晨報與交易觀點截圖(純文字格式)。
- 版面與格式:採用單欄純文字排版,搭配襯線字體(Serif font),文意流暢且結構清晰,以數字編號 1 至 5 進行主題分割,子項目採用小寫羅馬數字(i., ii.)。
- 出處與來源:根據內容中提及的人名與專業術語(例如 Prime Brokerage / PB book、Rich Privorotsky、David Mericle、Brian Garrett 等高盛策略師與經濟學者名字),此圖為機構級美股與宏觀市場分析報告之頁面截圖。
2. 所有可見文字(逐字擷取)
以下為圖片中出現的所有英文文字完整擷取,已完全保留原始大小寫、標點符號、縮寫與空格:
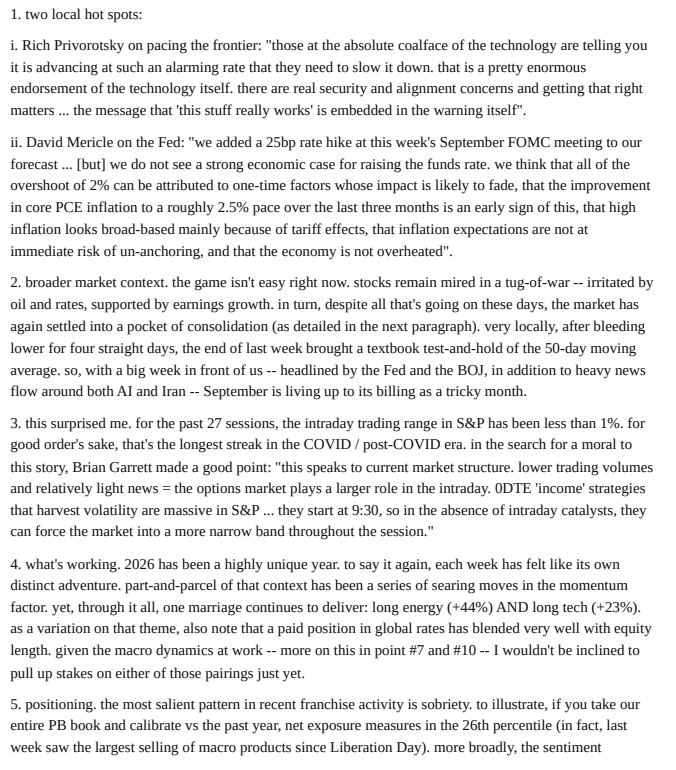
1. two local hot spots:

i. Rich Privorotsky on pacing the frontier: "those at the absolute coalface of the technology are telling you it is advancing at such an alarming rate that they need to slow it down. that is a pretty enormous endorsement of the technology itself. there are real security and alignment concerns and getting that right matters ... the message that 'this stuff really works' is embedded in the warning itself".

ii. David Mericle on the Fed: "we added a 25bp rate hike at this week's September FOMC meeting to our forecast ... [but] we do not see a strong economic case for raising the funds rate. we think that all of the overshoot of 2% can be attributed to one-time factors whose impact is likely to fade, that the improvement in core PCE inflation to a roughly 2.5% pace over the last three months is an early sign of this, that high inflation looks broad-based mainly because of tariff effects, that inflation expectations are not at immediate risk of un-anchoring, and that the economy is not overheated".

2. broader market context. the game isn't easy right now. stocks remain mired in a tug-of-war -- irritated by oil and rates, supported by earnings growth. in turn, despite all that's going on these days, the market has again settled into a pocket of consolidation (as detailed in the next paragraph). very locally, after bleeding lower for four straight days, the end of last week brought a textbook test-and-hold of the 50-day moving average. so, with a big week in front of us -- headlined by the Fed and the BOJ, in addition to heavy news flow around both AI and Iran -- September is living up to its billing as a tricky month.

3. this surprised me. for the past 27 sessions, the intraday trading range in S&P has been less than 1%. for good order's sake, that's the longest streak in the COVID / post-COVID era. in the search for a moral to this story, Brian Garrett made a good point: "this speaks to current market structure. lower trading volumes and relatively light news = the options market plays a larger role in the intraday. 0DTE 'income' strategies that harvest volatility are massive in S&P ... they start at 9:30, so in the absence of intraday catalysts, they can force the market into a more narrow band throughout the session."

4. what's working. 2026 has been a highly unique year. to say it again, each week has felt like its own distinct adventure. part-and-parcel of that context has been a series of searing moves in the momentum factor. yet, through it all, one marriage continues to deliver: long energy (+44%) AND long tech (+23%). as a variation on that theme, also note that a paid position in global rates has blended very well with equity length. given the macro dynamics at work -- more on this in point #7 and #10 -- I wouldn't be inclined to pull up stakes on either of those pairings just yet.

5. positioning. the most salient pattern in recent franchise activity is sobriety. to illustrate, if you take our entire PB book and calibrate vs the past year, net exposure measures in the 26th percentile (in fact, last week saw the largest selling of macro products since Liberation Day). more broadly, the sentiment
3. 結構化內容還原
以下將圖片中的 5 大核心分析重點進行結構化整理:
| 編號 | 分析主題 | 核心觀點 / 數據與引述內容 |
|---|---|---|
| 1 | 焦點議題 (Hot Spots) | i. AI 科技前沿 (Rich Privorotsky):站在技術第一線的人員警告進展速度過快需要放緩,這反而是技術本身極強的背書,雖然安全與對齊(alignment)問題至關重要,但警訊本身即代表「這項技術真的有效」。 ii. 聯準會利率展望 (David Mericle):團隊在 9 月 FOMC 預測中加入 25bp 升息,但認為缺乏升息的強烈經濟理由;核心 PCE 通膨近 3 個月放緩至 2.5% 左右,高通膨主要由關稅效應造成,通膨預期未脫錨,經濟並未過熱。 |
| 2 | 宏觀與大盤背景 (Broader Market) | 美股陷入拉鋸戰(受原油與利率干擾,但有企業盈餘支撐);在連續 4 天下跌後成功守住 50 日均線;面臨關鍵央行週(Fed 與 BOJ)及 AI、伊朗新聞流。 |
| 3 | 標普500指數波動度與市場結構 | 標普 500 指數連續 27 個交易日盤中振幅低於 1%,創疫情以來最長紀錄。 原因分析 (Brian Garrett):低成交量與淡靜消息面使選擇權市場主導盤中走勢,大量收割波動率的 0DTE(當日到期)收益策略壓制了指數盤中波幅。 |
| 4 | 當前有效交易策略 (What's Working) | 2026 年市場主線:做多能源(+44%)與做多科技(+23%)的雙強組合持續帶來極佳報酬;全球利率空頭/支付端部位與股票多頭搭配良好。 |
| 5 | 機構資金定位與曝險 (Positioning) | PB 券商機構客戶持倉克制:淨曝險部位處於過去一年第 26 百分位數;上週出現自「解放日」(Liberation Day)以來最大的宏觀產品拋售潮。 |
4. 視覺元素分析
- 色調與背景:採用簡潔的白色背景與深色字體,無額外色彩渲染或圖示背景。
- 圖表與標誌:圖中未包含任何 K 線圖、圓餅圖或品牌標誌,屬於純文字型態的研究簡報。
- 字體與邊距:使用了帶有襯線(Serif)的印刷字體,文字排版緊湊,兩端對齊良好。
- 截斷特徵:第 5 點最後一句話
more broadly, the sentiment在頁面底部截斷,表示本圖為多頁報告中的第一頁或前半部分截圖。
5. 上下文與推測用途
- 主題範疇:涵蓋機構視角下的美股市場結構分析、0DTE 選擇權對指數波動度的鎖定效應、聯準會與日本央行政策動向、科技與能源類股雙主流表現,以及券商 Prime Brokerage 客戶的持倉曝險水準。
- 潛在用途:主要供機構投資人、基金經理人或量化交易員掌握當前市場交易結構、尋求資產配置組合策略(如 Long Energy + Long Tech)以及評估大盤盤中低波動度的結構因素。
高盛美股宏觀與市場結構分析
本圖片為機構市場研究報告的截取頁面,內容深入分析了美股市場結構與總體經濟動向。報告重點指出標普500指數受0DTE選擇權收益策略壓制,已連續27個交易日盤中振幅低於1%,同時探討了聯準會升息預期、能源與科技類股的雙強表現,以及機構客戶淨曝險處於歷史低位等關鍵數據。